Switzerland’s CHFD tests conditional payments. Dispute resolution will be decisive
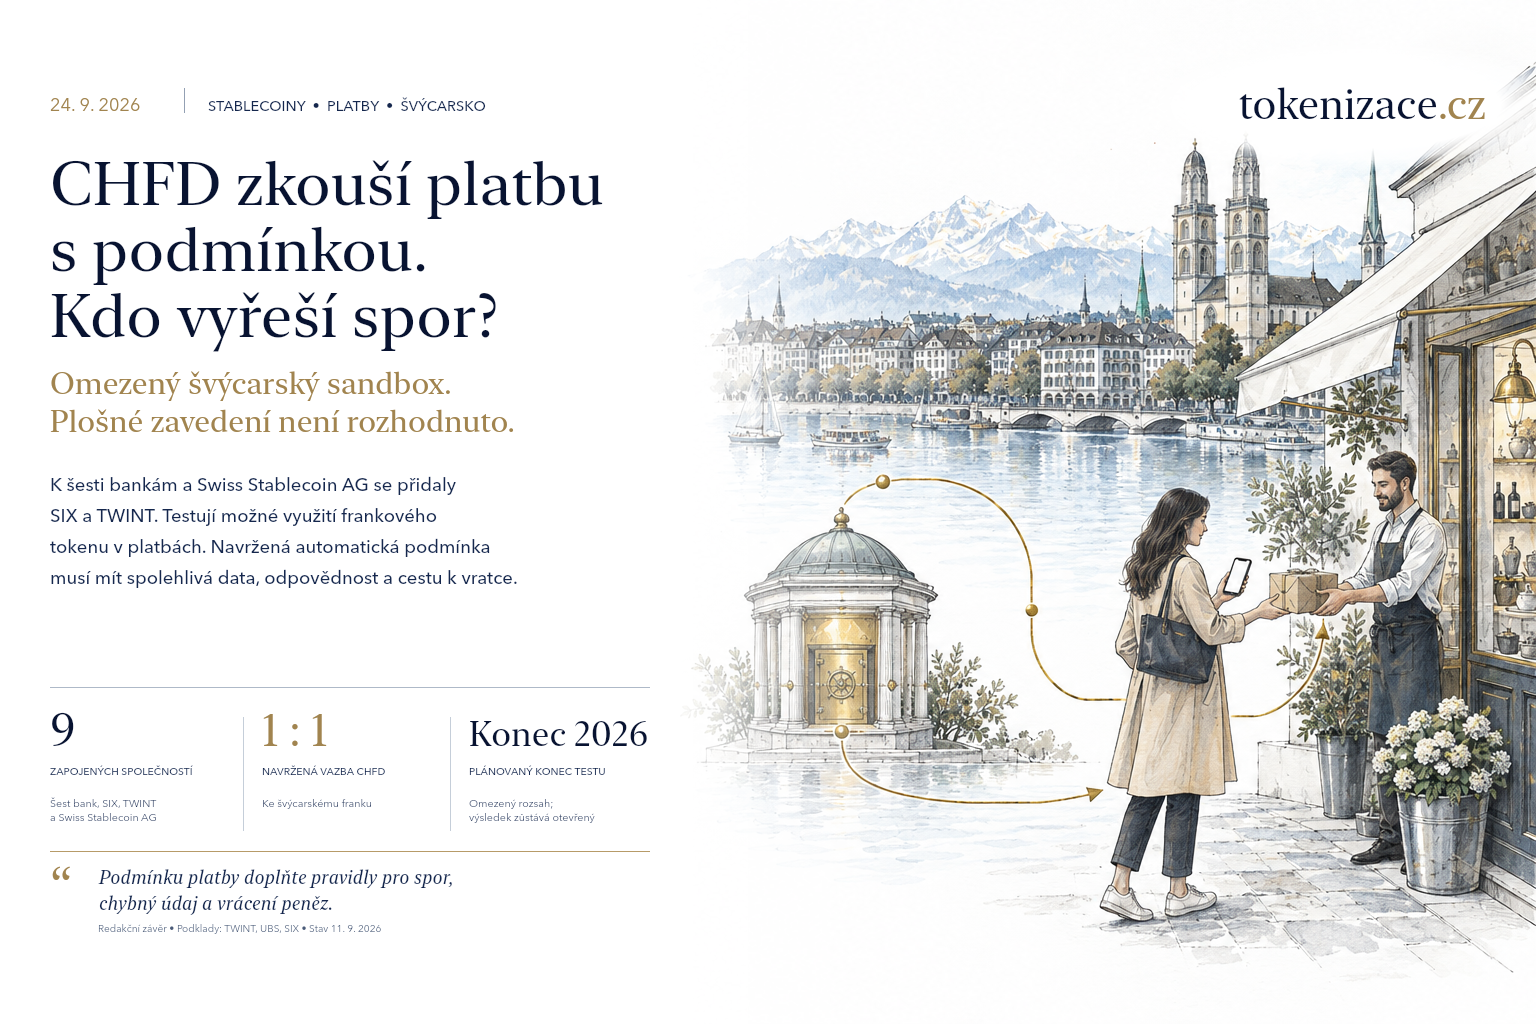
CHFD is running a limited trial involving nine companies. A usable conditional payment needs clear responsibility and a dispute procedure, not just a fast transfer.
Take the full article to your ChatGPT, Claude or Gemini and explore what it means for your work.
Paying only once a condition has been met sounds simple. For a ticket, the condition may be a valid transfer to the buyer; for a used camera, receipt of the item. The difficulty arises when seller and buyer disagree about what actually happened. Fast payment infrastructure does not adjudicate their dispute by itself.
That is precisely why the latest step in Switzerland’s CHFD project deserves attention. The involvement of financial infrastructure provider SIX and payment app TWINT opens a practical discussion about linking bank money, digital assets and everyday purchases. For Czech and Slovak companies, the most interesting part of the experiment is the design of the business process: who confirms the condition, who can suspend payment and who returns the customer’s money if the transaction falls through.
Summary for readers
- CHFD operates in a limited Swiss trial. The addition of further partners does not announce general availability for TWINT customers.
- Besides software, a conditional payment needs reliable input data, contractual responsibility and a route to remedy.
- A company should compare the entire transaction, including complaints, conversion and refunds. Transfer speed alone is insufficient to assess the benefit.
1. What exactly the Swiss announced
TWINT’s announcement of 8 September lists nine participating companies: UBS, PostFinance, Sygnum, Raiffeisen, Zürcher Kantonalbank, BCV, SIX, TWINT and Swiss Stablecoin AG. The technical platform has been operational since the end of June. It is operated by CHFD Infrastruktur AG, a subsidiary of Swiss Stablecoin AG; CHFD is designed with a one-to-one link to the Swiss franc.
Testing is to continue until the end of 2026 with limited participants and transactions. No decision has been made on commercial rollout. Use cases under consideration include marketplaces, tickets, public payments and institutional settlement. UBS’s April announcement had already outlined joint testing by banks and the technical infrastructure of Swiss Stablecoin AG.
It cannot be inferred from this that every participating bank separately issues the token, guarantees the entire project or offers it to all customers. Participation in the initiative, operation of infrastructure and the obligation to a holder are different roles. A public announcement is not a set of contracts allocating all of them.
2. SIX and TWINT bring experience from both ends of a transaction
In its corporate overview, SIX describes services ranging from trading through settlement and custody to payment infrastructure. TWINT presents its app as a tool for shopping in stores and online, as well as personal payments. Their experience can thus meet in a transaction that begins with a customer order and ends in financial settlement.
This is an editorial interpretation of the partnership’s significance, not a published plan for a specific integration. SIX’s participation does not automatically connect CHFD to all of its markets. Nor does TWINT’s presence demonstrate that the new token has appeared in ordinary users’ wallets.
This distinction is useful when designing a service. A payment screen may promise a simple purchase, while the banking side deals with quite different questions: availability of money, authority to sign instructions and operation during a failure. A good pilot must connect both perspectives in one specific business case. Otherwise, it produces an impressive demonstration that neither accounting nor customer support can use.
3. Software can evaluate a condition, but someone must define it
Imagine a hypothetical ticket sale. The buyer deposits funds, the system verifies the transfer of a valid right of admission and then releases the amount to the seller. Such a connection can prevent one party fulfilling its obligation while the other does not. This is our illustration of a possible arrangement, not a description of a published CHFD implementation.
The decisive question is how the system knows that the ticket is valid. If it obtains data directly from the organiser, it must address the organiser’s availability and authority to change the record. If it relies on a marketplace, it also inherits its errors. A photograph of a ticket sent by the seller is different evidence from confirmation by the system controlling entry to the event.
Goods present the same problem. A carrier’s record of “delivered” confirms a different fact from “delivered without defects”. The payment rule must match the commercial agreement. An excessively narrow condition harms the buyer; an overly loose one allows the seller’s money to be withheld. More precise software cannot replace missing agreement on when performance has been properly completed.
4. Complaints belong in the design from the start
TWINT’s existing services provide a clear route when a customer disputes a purchase payment: first contact the merchant, then the app’s support service if that fails. Purchase and communication records should help. This is how the official procedure for disputed purchases describes it. These are not rules for the new CHFD pilot, but a reminder of how specific the customer journey must be.
A conditional payment must distinguish at least three points: money is waiting for a condition, payment has been completed and a new entitlement to a refund has arisen. Correcting a completed transaction may involve a separate payment. It need not mean erasing the original transaction or being able to rewrite accounting history at will.
Service design should therefore include deadlines for submitting evidence, a person responsible for the decision and a source of funds for refunds. If the system permits exceptional suspension, it needs narrowly defined powers and a record of every use. Without this allocation, automation may merely move a dispute from a counter to inaccessible technical support.
Fraud must be addressed separately. TWINT’s safety recommendations encourage checking the recipient and caution on online marketplaces. A trustworthy application does not give every counterparty a trustworthy identity. Customer verification, account protection and the seller’s honesty are different things.
5. A link to the franc does not say who owes the franc
The one-to-one figure is often the most prominent feature in stablecoin presentations. From a financial perspective, however, we still need to identify the debtor, the composition and custody of reserves, the redemption right and the procedure in the event of failure. For CHFD, these conditions cannot be fully assembled from press releases alone. Even the names of major partners are no substitute for issuance documentation.
Comparison with another Swiss project helps. In its Helvetia materials, the Swiss National Bank describes that project’s wholesale digital money as the legal and economic equivalent of central bank deposits in a different technological form. A similar status as a claim against the central bank is not announced for CHFD. The two projects cannot be combined under one “digital franc” category without further explanation.
In its stablecoin guidance, FINMA notes, among other things, bank guarantees used by some issuers and the associated risks for banks and holders. This is general regulatory context. It does not establish that CHFD uses that particular structure, or confirm that its holders are protected by the same regime as an ordinary bank account.
6. Testing and legislative change run on different timelines
In October 2025, the Federal Council opened a consultation on amending the Financial Institutions Act. It proposed new licensing categories and additional rules for stablecoins and crypto services. The consultation period ended on 6 February 2026. This document establishes a proposal and its objectives, not the automatic entry into force of the entire intended regime.
The word sandbox in the banks’ announcement therefore cannot be used as universal regulatory confirmation. The actual test conditions and any individual authorisations must be read. Published cooperation among private companies does not by itself establish a special statutory exemption, supervisory approval of every business model or readiness for a general offering.
For a business owner, the approach to uncertainty matters. A commercial contract may permit a small test with limited impact and a predetermined end. Investment in a company-wide payment process, however, needs firmer documentation and a clear fallback. These two phases should have different budgets and success criteria.
7. Czech and Slovak companies start with a specific transaction
A Czech supplier selling to a Swiss customer could hypothetically link the release of payment to acceptance of a delivery. The benefit depends, however, on whether the customer accepts the same conditions and whether the company can use the funds quickly. Receiving a token does not complete the entire financial process if accounting needs a bank statement or suppliers require Czech crowns or euros.
Before an experiment, it makes sense to map one real transaction: who orders, who accepts delivery, how complaints work, when payment falls due and what conversion to the company’s currency costs. The Swiss franc also fluctuates against both the crown and the euro. The token’s stability against the franc does not remove foreign trade currency risk.
Separating data is equally important. The carrier needs to confirm delivery but need not see the cost of financing. The payment operator does not need the entire contents of a commercial dispute. A model requiring complete documentation to be shared with every participant may create more work than today’s accounting links. A more economical confirmation of the single decisive fact can itself be a benefit.
Finally, actual service availability and cross-border conditions must be checked. This Swiss experiment is not an offer of access to every Czech or Slovak company. Its existence does not establish authorisation to offer the same product in another jurisdiction.
Waiting for the condition has a particular place in the financial comparison. The customer’s funds may already be blocked while the merchant cannot yet use them. Who finances this interval, and who bears the cost of a prolonged dispute? If the new model merely shifts it to a smaller supplier, it does not automatically improve the transaction’s overall economics. A pilot should compare the actual day on which money becomes usable with the existing contract, including any advance payment, retained amount and carrier deadlines. Only such a comparison will show whom the service benefits.
8. How to recognise a useful experimental result
We would consider a transaction convincing if the published results included not only the speed of a successful payment, but also the time taken to resolve an exception, the proportion of manual interventions and refund costs. These are our editorial measures, not announced CHFD indicators.
A control test should include an unavailable data provider, customer disagreement and an incorrectly entered recipient. In each situation, it must be clear who decides, how the outcome is evidenced and how operations are restored. For an ordinary purchase, such a workable remedy is often more valuable to the customer than a marginally faster confirmation.
Any final CHFD evaluation will therefore be interesting primarily for its specificity. If it shows how to allocate responsibility among the bank, technical operator, merchant and payment app, it will provide useful experience beyond Switzerland too. What can be transferred is a verified process and its economics. The partner list alone cannot create that value.
Sources
Methodological note
All ten sources listed were opened during research on 11. 9. 2026. Ledger Insights serves as a lead; precise project information comes from participants’ announcements. A press release is not independent verification of operational results. Hypothetical examples, proposed allocations of responsibility and evaluation criteria are editorial analysis. Published sources do not provide complete CHFD issuance documentation, specific limits, test results or a binding date for a commercial offering. The historical consultation is not described as a new legal regime in force. Any subsequently published changes should be added before the planned publication.
Disclaimer
This article is for information and educational purposes. It does not constitute investment recommendations, legal, tax or payment advice, or an offer of any specific service. Suitability and legal conditions of use must be assessed according to the specific product, contracts and jurisdiction.
What this means for you
AI puts the article in the context of your role, company and industry. Choose the one working document you need now.
Saved outputs and notes are private. Making your profile public does not share them with other users.
Loading account…
Context and outlook
Loading…
Open the full category →Comments
No comments yet. Be the first!
Recommended reading
Related reading based on this article’s topic and category.