Luxembourg plans a digital sovereign bond. A billion-euro issue will test more than the technology
Luxembourg’s government has announced plans for a digital sovereign bond of at least one billion euros with an expected ten-year maturity. The timing will depend on investor interest and market conditions; the size of the issue alone does not create a liquid secondary market.
Take the full article to your ChatGPT, Claude or Gemini and explore what it means for your work.
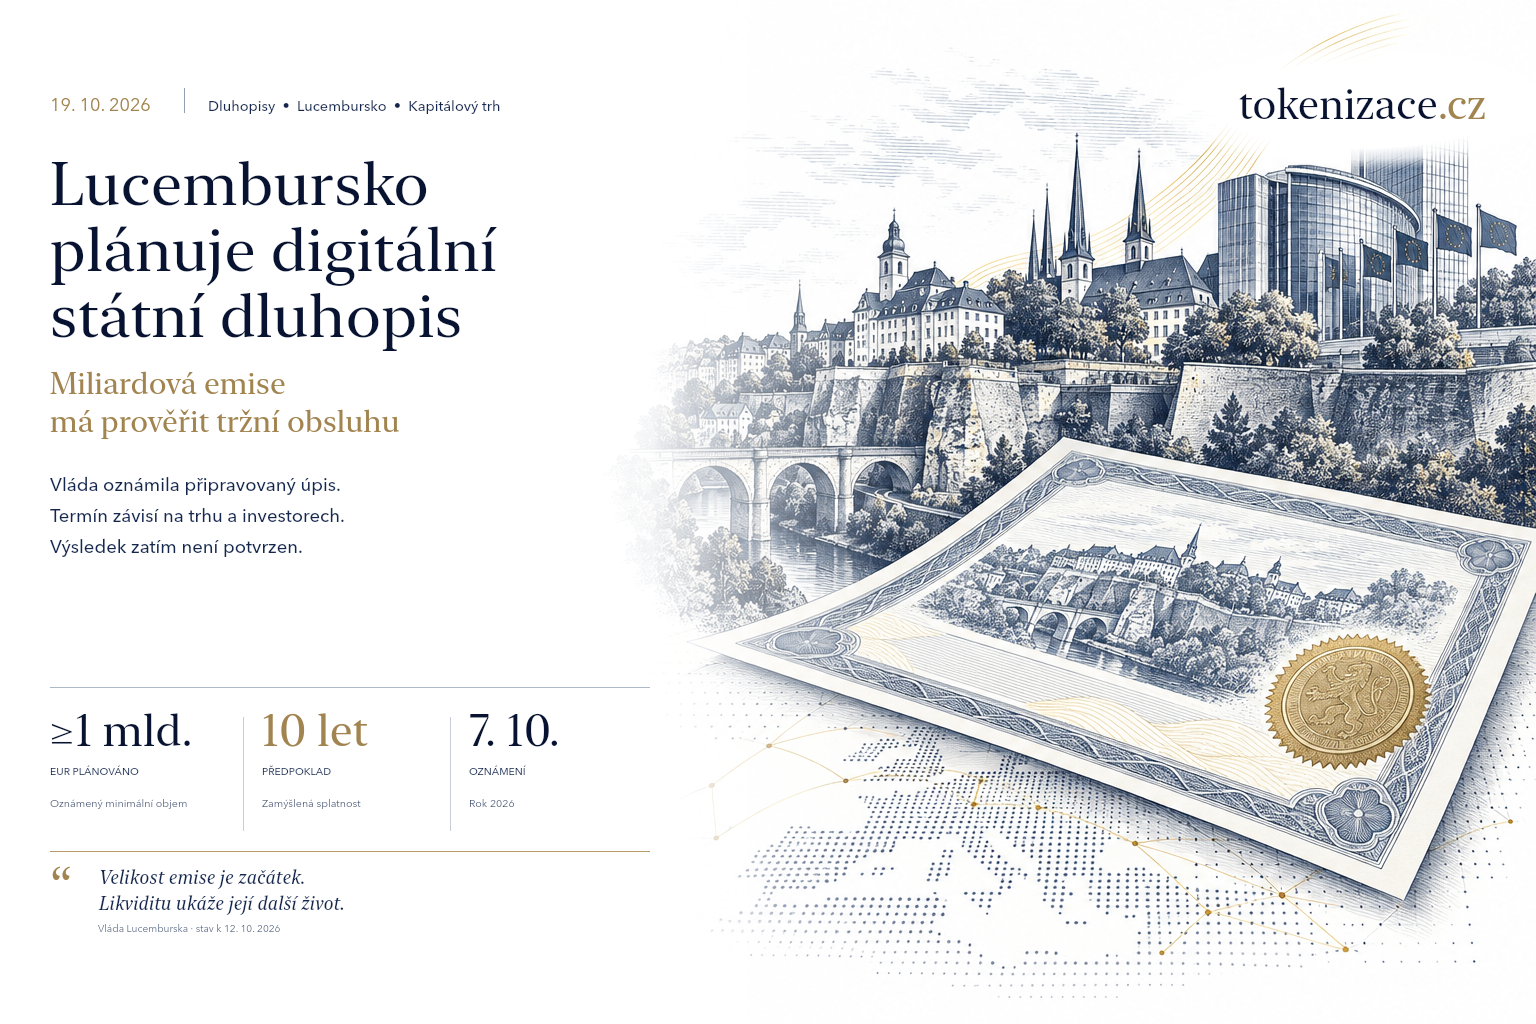
The state is preparing a digital bond issue of at least one billion euros. The decisive question will be whether the new form of record-keeping fits into the daily work of investors, asset managers and banks.
Summary for readers
- The government has announced plans for an issue of at least one billion euros with an expected ten-year maturity.
- The timing will depend on investor interest and market conditions.
- The size of the issue alone does not create a liquid secondary market.
What has been announced and what is still missing
On 7 October, Luxembourg’s government described a forthcoming sovereign bond using blockchain technology. It is to be denominated in euros, governed by Luxembourg law and listed on the Luxembourg Stock Exchange. The announcement envisages at least one billion euros and a ten-year maturity. Eligibility for Eurosystem operations is presented as an expectation, not as an unconditional feature of every digital instrument. Government announcement.
As of the source cutoff on 12 October, this announcement cannot establish that subscription has been completed, what the final yield is or who the investors are. This article’s publication date is an editorial plan; it provides no evidence that the transaction has taken place in the meantime. This distinction is particularly important in sovereign financing, which responds to market conditions.
What a large issuer can demonstrate
In our analysis, the significance of a sovereign issue lies in the number of practical connections that must work simultaneously. An investor must be able to buy, account for, value, manage and potentially sell the bond. A bank needs to process its client’s instruction. A fund manager must be able to document what it holds and who is authorised to deal with the assets.
A smaller demonstration transaction may handle these steps with intensive individual assistance. A larger subscription will show how many activities are repeatable and how many depend on manual coordination. Volume therefore gives the project weight, but without subsequent operational data it does not demonstrate cost savings.
Liquidity comes from subsequent trades
One billion euros of issued bonds is not the same as one billion euros available for immediate trading. Some investors may hold the instrument to maturity. The ability to exit a position depends on buyers, available prices, order sizes and the settlement route.
Data on secondary trading would therefore be useful in assessing the outcome: whether trades actually take place, how wide the bid–ask spread is and which institutions can service the instrument without a special exception. For now, these are questions for a future assessment, not known shortcomings of Luxembourg’s project.
Lessons for a Czech issuer
A Czech or Slovak company cannot automatically obtain the terms available to a state. It can, however, learn from the preparation process. First identify the target investor and verify its usual infrastructure; then choose the record-keeping and distribution route. Reversing that order may produce a technically finished product that an investor cannot conveniently include in its portfolio.
Before commissioning an issue, it would make sense to map five steps: purchase, holding, receipt of payments, transfer and exit from the investment. Each needs a responsible institution, an expected cost and a procedure for handling errors. A digital format may simplify some activities, but responsibility for them must remain traceable.
Luxembourg’s plan will be interesting precisely because of how many of these connections it can handle under ordinary market conditions. The first measure of success is a completed issue that can be serviced. Its subsequent life will reveal its long-term value.
Sources
Methodological note
This article distinguishes institutional announcements from the editorial team’s own analysis. The sources include direct material about the event and background on the topic; their inclusion does not mean that they all describe the same transaction. The examples and questions for companies are the author’s interpretation, not findings about a particular client. The planned publication date does not advance the cutoff date for verification of the sources.
Disclaimer
This text is for information and education. It does not constitute investment, legal, tax or accounting advice or an offer of a financial service. Any application requires an individual assessment. The institutions mentioned are neither partners nor guarantors of Tokenizace.cz.
What this means for you
AI puts the article in the context of your role, company and industry. Choose the one working document you need now.
Saved outputs and notes are private. Making your profile public does not share them with other users.
Loading account…
Context and outlook
Loading…
Open the full category →Comments
No comments yet. Be the first!