The digital euro seeks further practical use cases. Companies can test payments before an issuance decision
The ECB has opened another round of the digital euro innovation platform, with experimentation and exploration streams for 2027. Applications can be submitted until 9 November 2026; the decision to issue the currency is to follow legislation.
Take the full article to your ChatGPT, Claude or Gemini and explore what it means for your work.
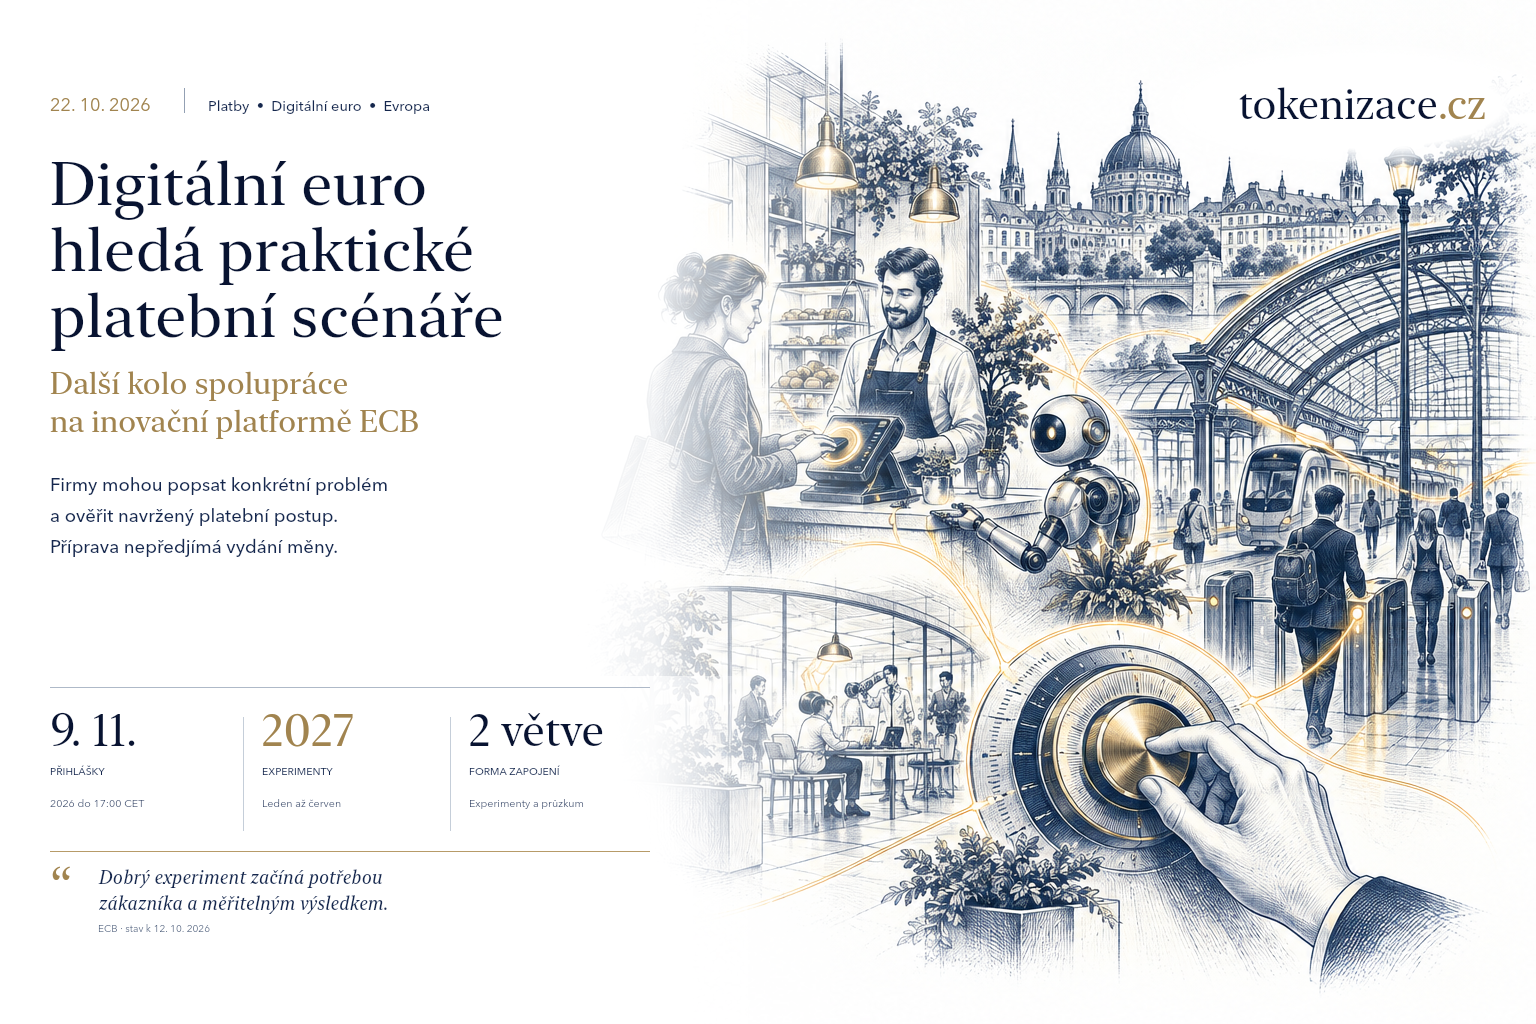
The European Central Bank is opening another round of cooperation on possible uses of the digital euro. For companies, it offers an opportunity to describe precisely the payment problem they want to solve and test the proposed process.
Summary for readers
- The call includes experimentation and exploration streams for 2027.
- According to the ECB, applications can be submitted until 9 November 2026 at 17:00 Central European Time.
- The final decision to issue the digital euro is to follow the adoption of legislation.
Two streams with different purposes
The ECB announced the new round of the innovation platform on 28 September. It plans experiments from January to June 2027; topics include electronic receipts, payments involving multiple payers or recipients, conditional payments and app functions. In the first two quarters, the exploration stream is to examine, among other things, payments involving artificial intelligence and public uses, such as transport and services. ECB call.
The experimental platform does not introduce a new currency into general circulation. The ECB explicitly separates preparation from the future issuance decision, which is to come only after the legislative process. Nor should the list of topics be read as a binding catalogue of final functions for all users.
Start with a specific purchase
A useful business proposal need not start with technology. It could describe an ordinary situation in which today’s payment creates unnecessary work. For example, a hypothetical joint purchase of a service by several people: who enters the amount, when is the payment considered complete, and how is a refund of one share handled? Each answer affects both the interface and the merchant’s responsibility.
Another illustrative question is how to connect a payment with a receipt. The customer needs to find the document, the merchant needs to assign it correctly, and both must understand which data are transferred. Adding a digital instrument does not settle that agreement on its own. It can, however, offer an opportunity to test it across the entire process.
A payment condition and a property of money
It is important not to confuse a conditional payment instruction with a restriction on how the money itself can be used. In an illustrative arrangement, the parties may agree that a payment will be executed once a condition is met. That is a different question from determining which goods the recipient may subsequently buy with their money. This article uses the distinction to explain service design; it does not claim that specific future rules have already been approved.
For a company, the test should show who confirms fulfilment of the condition and what happens in a dispute. If the merchant, customer and intermediary understand the same state differently, faster technical execution may merely accelerate the problem. Clear information about acceptance, waiting and completion of an instruction therefore belongs in a well-defined proposal.
A payment agent needs boundaries
Artificial intelligence raises another practical question. Which action can software prepare on its own, and when should it obtain human consent? An illustrative specification can set a maximum amount, permitted purpose, validity period and a right to revoke. Without these boundaries, it would be difficult to assess whether an agent fulfilled the user’s wishes.
What Czech companies can prepare
An interested applicant should first read the call’s conditions and verify whether it fits the required role. This article does not assess its eligibility. A practical preparation is a one-page description of the scenario: the current problem, participants, desired improvement, verification of the outcome and the procedure when something goes wrong.
That document has value even without participation in the platform. It helps distinguish a useful payment function from general enthusiasm for new infrastructure and provides a specific benchmark for a future pilot.
Sources
Methodological note
This article distinguishes institutional announcements from the editorial team’s own analysis. The sources include direct material about the event and background on the topic; their inclusion does not mean that they all describe the same transaction. The examples and questions for companies are the author’s interpretation, not findings about a particular client. The planned publication date does not advance the cutoff date for verification of the sources.
Disclaimer
This text is for information and education. It does not constitute investment, legal, tax or accounting advice or an offer of a financial service. Any application requires an individual assessment. The institutions mentioned are neither partners nor guarantors of Tokenizace.cz.
What this means for you
AI puts the article in the context of your role, company and industry. Choose the one working document you need now.
Saved outputs and notes are private. Making your profile public does not share them with other users.
Loading account…
Context and outlook
Loading…
Open the full category →Comments
No comments yet. Be the first!